

Acorns: Save & Invest Money

- 77.82K Reviews
- 4.7
- Downloads
- 10,000,000+
Our take on Acorns: Save & Invest Money from Appgk
Saving money often fails before investing even begins. I might intend to put a little aside after each purchase, then forget, postpone it, or decide that the amount is too small to matter. Acorns approaches that everyday problem by turning small financial habits into a more deliberate investing routine. It is a finance app from Acorns that focuses on building a plan around stocks and exchange-traded funds, rather than asking me to choose individual companies one by one.
My impression is that it works best as a bridge between “I should start investing” and actually creating a repeatable habit. It is free to download, rated for Everyone, and has become a widely used app, with a 4.7 average from around 407 thousand ratings and more than 10 million installs. Those figures suggest that the basic idea is easy for many people to understand, but popularity does not remove the need to check whether its hands-off style matches your goals.
From spare change to an investing routine
The starting point is behavior, not stock picking
When I open a service like this, I am not usually looking for a trading terminal. I want a manageable way to begin, especially if I do not yet feel comfortable researching companies, comparing funds, or deciding how to divide a portfolio. The central appeal here is the attempt to make investing part of normal money behavior instead of a separate task that requires constant attention.
That distinction matters. A person who wants to buy a particular technology company, place advanced orders, or react quickly to market movements will probably find this approach too limited or too indirect. Someone who wants a structured plan for long-term exposure to stocks and ETFs may find the simpler path reassuring.
Best Parts of Acorns: Save & Invest Money
Things to Keep in Mind About Acorns: Save & Invest Money
I would begin by treating the app as a system for consistency, not as a promise of quick returns. Markets can rise and fall, and an automated contribution does not make investing risk-free. The useful question is whether the workflow helps me contribute money I can genuinely leave invested without interfering with rent, bills, emergency savings, or other priorities.
Setting up the plan without rushing the decision
The first meaningful step is choosing the kind of investing routine I can maintain. That sounds obvious, but it is where many beginners make a mistake: they choose an ambitious amount because it looks good on paper, then stop when their monthly budget becomes tight. I would start with a contribution level that feels almost boring. A sustainable habit is more valuable than an impressive first deposit that creates stress later.
News and Features Related to Acorns: Save & Invest Money

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
The app’s emphasis on a smart investing plan can reduce the pressure of making every decision manually. Instead of opening a brokerage chart and wondering which stock to buy, I can focus on the bigger questions: how much risk am I willing to accept, how long can I stay invested, and what role should this account play alongside cash savings or retirement plans?
This is also the point where I would slow down and read each screen carefully. A friendly interface can make financial choices feel effortless, but “easy to select” does not mean “unimportant.” I would review the selected plan, the funding source, the timing of transfers, and any explanation of how money is allocated before confirming anything.
Don't want to read the full review?
Turning ordinary spending into a trigger
The most interesting use case is for someone whose difficulty is remembering to save. Imagine buying lunch, commuting home, and making a few small purchases during the week. Rather than relying on a separate manual transfer at the end of the month, the Acorns workflow is designed around connecting daily money activity with investing behavior. The psychological advantage is that the saving decision happens closer to the purchase, when the habit is easier to notice.
I would not use this casually without checking the combined effect. Small amounts may feel invisible individually, but several automatic movements can still affect the balance available for groceries or bills. My practical tip is to watch the first cycle closely, compare the transfers with my real cash flow, and adjust the routine before it becomes inconvenient.
Screenshots
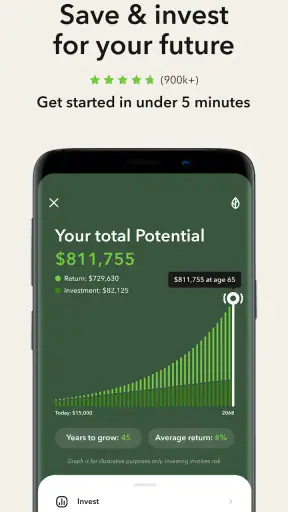
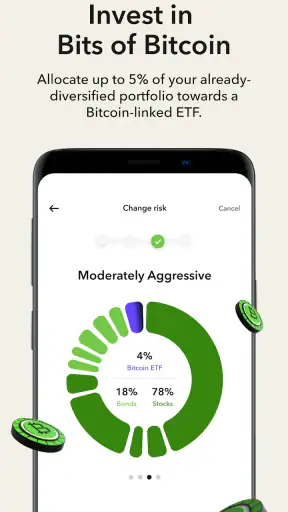
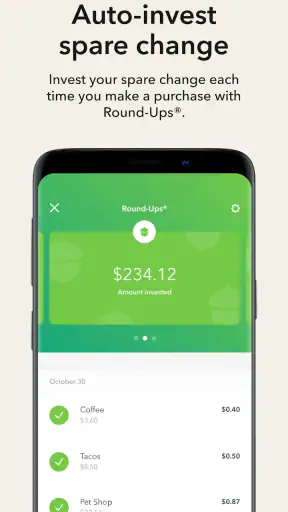
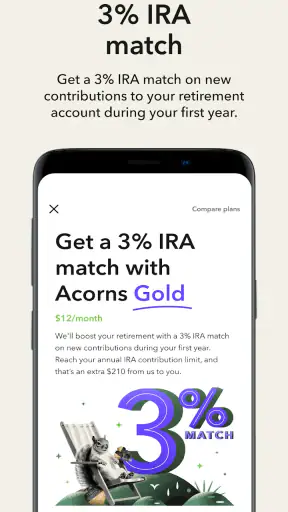
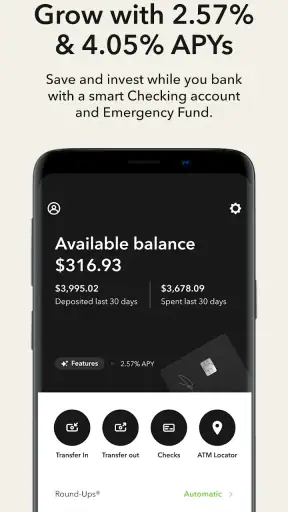
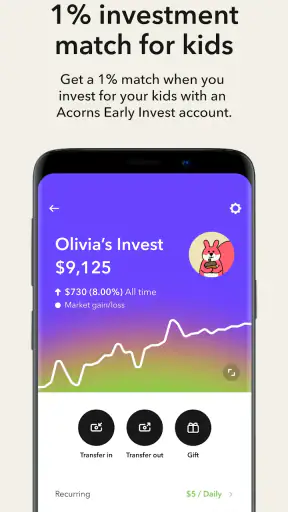
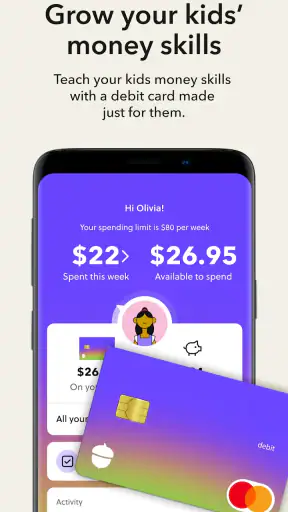
This is one of the app’s less obvious trade-offs: automation removes mental effort, but it also removes some moments when I would otherwise notice that money is leaving my spending account. The best experience comes from pairing automation with a weekly or monthly review, even if the app itself is intended to reduce daily supervision.
What happens between the bank account and the portfolio
The handoff from everyday money to investments is where trust matters most. I want to know which account is being used, when funds are expected to move, and whether the amount fits my available balance. A beginner may assume that a small transfer cannot cause trouble, but timing still matters when a purchase lands just before a bill or when the account balance is lower than expected.
I would create a simple personal rule: keep a buffer in the connected spending account and do not count pending investment money as available cash. That rule is useful with any automated finance tool, but it is especially important here because the attraction is precisely that the process can continue in the background.
The next handoff is from the app’s plan to the underlying investment mix. The benefit is convenience: I do not have to make a fresh stock decision for every contribution. The limitation is control. If I want to build a very specific portfolio, exclude a particular sector, or manage tax and allocation details with precision, a traditional brokerage may be a better fit.
Why the ETF approach changes the experience
For a new investor, stocks and ETFs do not feel interchangeable. Buying one company can create a concentrated position, while an ETF can provide exposure to a broader collection of holdings. The app’s plan-based approach makes that broader structure easier to approach than selecting securities individually.
That does not mean the result is automatically right for every person. A diversified fund can still lose value, and a portfolio that feels comfortable during a rising market may feel very different during a decline. I would choose this style only if I am prepared to leave the money alone through ordinary market uncertainty rather than checking the balance after every movement.
The useful insight is that simplicity changes the main skill required. With a self-directed brokerage account, the challenge is often choosing and managing investments. With this app, the challenge becomes setting a sensible plan, maintaining adequate cash flow, and resisting the urge to interfere whenever the market looks uncomfortable.
The everyday workflow I would actually use
Here is how I would fit it into a normal week. First, I would decide on a modest investing target after accounting for fixed expenses and emergency savings. Next, I would connect the appropriate funding source and confirm the plan rather than tapping through quickly. Then I would let the routine run while checking my bank balance and the app’s activity at a regular interval.
At the end of the first month, I would compare the expected behavior with what actually happened. Did the transfers arrive when I thought they would? Did they make spending feel tighter? Did I understand where the money was being invested? If the answer to any of those questions is no, I would change the setup before increasing the amount.
This review step is more important than it sounds. Automated investing is often sold as something that can be forgotten, but “forgotten” should mean no longer requiring daily decisions, not no longer requiring oversight. A short recurring check protects the convenience from turning into financial blind spots.
Where the result is genuinely useful
The outcome I would expect is not a dramatic transformation overnight. It is a visible investing habit that can continue without me researching a new stock every week. For a first-time investor, that reduction in friction can be meaningful. The app gives the routine a destination: money moves from ordinary financial activity toward a portfolio built around stocks and ETFs.
It can also help someone who has already decided to invest but keeps waiting for the “right” time or the “perfect” amount. A plan-based approach encourages action without requiring expert-level market knowledge. I particularly see value for people who want to learn by observing a simple system while keeping their decisions limited.
Still, I would measure success by consistency and suitability, not by a short-term balance increase. The market can move in either direction, and an app cannot make an unsuitable contribution amount safe. If the account is funded with money needed soon, the workflow is already being used for the wrong job.
Questions I would settle before relying on it
One natural question is whether it is suitable for a complete beginner. In my view, yes, if “beginner” means someone who wants guidance and is willing to learn the basics of risk, diversification, and time horizon. It is less suitable if the person expects the app to explain every possible investment choice in depth or to guarantee a result.
Another question is whether it can replace an emergency fund. I would not treat an investment account as a substitute for cash reserved for urgent expenses. Investments can fluctuate precisely when I need access to the money, so I would establish a separate cash cushion before increasing automated contributions.
People also wonder whether automation means they can stop paying attention. I would answer no. Automation is helpful for execution, but I would still review the selected plan, connected funding source, contribution pattern, and account activity. That small amount of supervision is the handoff that keeps convenience aligned with reality.
A further question is whether this is better than a normal brokerage account. It depends on the job. A brokerage is usually the stronger choice for detailed control, individual security selection, advanced order types, or a highly customized portfolio. Acorns is more appealing when the priority is reducing decisions and making investing feel connected to everyday saving.
Where the flow breaks down
The first weak point is overconfidence in small contributions. Small, automatic amounts can build discipline, but they do not remove the need for adequate income, cash reserves, or a realistic time horizon. I would be cautious if the app’s convenience encouraged me to invest while carrying expensive debt or struggling to cover essential bills.
The second is the loss of control that comes with a guided plan. I may appreciate not having to choose every holding, but I also accept that the app is not designed around my every preference. Investors who want to rebalance manually, pursue a narrow strategy, or inspect a portfolio at a professional level may become frustrated.
The third is emotional discomfort during a downturn. A smooth setup can make investing feel almost like saving, yet the value can still change. If I am likely to stop contributions or withdraw at the first significant decline, I would rather spend more time learning about market risk before depending on this workflow.
There is also a practical limitation for people who want everything consolidated in one financial control center. The app may simplify investing, but it should not automatically become the place where I manage every financial goal. I would keep a clear view of spending, debt, cash savings, and other investments so that this account remains part of a plan rather than the entire plan.
Who should use it and who should look elsewhere
I would recommend giving it serious consideration to a new investor who wants a low-maintenance path into stocks and ETFs, has irregular trouble saving, and can commit money for the long term. It is also a reasonable fit for someone who prefers a guided experience over a screen full of charts and order controls.
I would point an experienced trader toward another type of service. If you need direct control over individual securities, sophisticated analysis, or rapid execution, the simplicity that helps beginners will feel restrictive. I would also suggest caution to anyone whose budget is too tight for automatic transfers or who has not yet built accessible emergency savings.
The app is free to download and has an Everyone age rating, which makes the initial barrier approachable. It was released in October 2014 and is currently listed as version 4.207.0 for operating systems from version 10 onward. Those details are useful when checking whether an older phone can run it, but compatibility is only one part of the decision; the financial workflow still needs to fit the user.
My final take after following the full path
What I like most is the clear behavioral idea: start with ordinary money decisions, pass a manageable amount into a guided investing plan, and let repetition do more of the work than willpower. The handoffs are convenient when they are understood, especially for someone who would otherwise leave investing on a to-do list forever.
What keeps me from calling it a universal solution is the same simplicity that makes it attractive. I give up some control, and I still need to monitor cash flow, understand market risk, and keep separate short-term savings. The app can make the first steps easier, but it cannot decide how much I can safely invest or whether this is the right account for a particular goal.
My honest recommendation is to use it as a structured starting point, not as a financial autopilot that deserves unlimited trust. Begin conservatively, inspect the first few transfers, understand the plan behind the portfolio, and review the result on a regular schedule. If that balance between convenience and oversight suits you, Acorns can turn a vague intention to invest into a routine that is much easier to maintain.
Acorns: Save & Invest Money FAQ
What is Acorns: Save & Invest Money, and how does it work?
Acorns is a personal finance and investing app designed to help users save and invest with minimal effort. Its main feature, Round-Ups, can automatically invest the spare change from linked purchases once it reaches a selected threshold. You can also make recurring deposits, choose an investment portfolio based on your goals and risk tolerance, and monitor your progress from the app.
Is Acorns suitable for beginners who have never invested before?
Acorns is particularly approachable for beginners because it simplifies many decisions involved in investing. During setup, the app asks about your financial goals, time horizon and comfort with risk, then suggests a diversified portfolio. The interface is easy to understand, although users should still learn the basics of market risk, fees and long-term investing before depositing significant amounts.
How much does Acorns cost, and are there any additional fees?
Acorns operates through subscription plans rather than being completely free. The cost and included features can vary depending on the plan available in your region, and some plans may include investing, retirement, checking or family-focused tools. Before subscribing, review the current pricing page carefully, since subscription charges can reduce returns, especially when maintaining a small account balance.
Can I lose money when investing through Acorns?
Yes. Acorns invests money in market-based portfolios, so the value of your account can rise or fall. Diversification may help reduce the impact of a poor-performing investment, but it cannot eliminate market losses or guarantee profits. Round-Ups and recurring contributions also do not make investing risk-free. Consider your goals, financial situation and risk tolerance before investing.
What do I need to use Acorns, and can I withdraw my money?
You generally need an eligible bank account or payment card, personal identification details and a supported country or region to open an Acorns account. After your account is verified, you can connect funding sources and begin investing. Withdrawals are usually requested in the app, but processing times, eligibility rules, tax consequences and account restrictions may apply.












